A rice cargo can sit at anchor for weeks over one wrong word in a payment clause. For Qatari importers bringing in bulk basmati, parboiled, or long grain rice from Pakistan, India, or Thailand, the payment term chosen before the ship even loads decides who carries the risk if something goes wrong. Get it right, and cargo clears smoothly with cash flow protected on both sides.
Rice import payment terms fall into a handful of proven structures: cash in advance, letters of credit, documentary collections, open account, and consignment. Each one shifts risk differently between the Qatari buyer and the overseas exporter. The right choice depends on how well the two sides know each other, the size of the order, and how much country and bank risk sits on either end of the deal.
For Qatar’s importers, distributors, and HORECA procurement teams, the stakes are practical. A confirmed letter of credit costs more but protects a large first order. A telegraphic transfer moves faster and cheaper but demands real trust in the supplier.
Key Takeaways
- Payment terms for rice imports range from fully secured (LC) to fully trust-based (open account), with CAD and TT sitting in between.
- Matching the payment method to the supplier relationship, order size, and country risk protects both cash flow and cargo.
- Shipping documents, bank confirmation, and contract clarity determine whether a payment term actually works as intended.
Which Payment Method Fits Your Rice Order?
The payment method that fits a rice order depends on the size of the shipment, how well the buyer knows the supplier, and how much payment risk each side can absorb. Rice trade runs on thin margins, so a mismatched payment term can turn a routine order into a cash flow problem or a stuck container.
Cash in Advance and Deposits
Cash in advance means the Qatari importer pays before the exporter ships. A partial deposit, often 20 to 30 percent, is common on first orders, with the balance due against shipping documents. This protects the seller but leaves the buyer exposed if the goods never arrive or arrive short of contract quality.
Bank-Backed Documentary Credits
Letters of credit and other documentary credits put a bank between the two parties. The issuing bank guarantees payment once the exporter presents documents that match the LC terms exactly. This is the standard choice for larger, first-time, or cross-border rice orders where trust has not yet been established.
Collections
Documentary collection, covering both cash against documents and documents against acceptance, uses banks to handle paperwork without a bank guarantee behind the payment. The bank simply exchanges documents for payment or a promise to pay, which shifts more risk onto the seller than an LC does.
Open Account
Open account terms let the buyer receive goods and documents before paying, usually on a set number of days after shipment or arrival. This favors the importer’s cash flow heavily and is generally reserved for long-standing supplier relationships with a strong payment history.
Consignment
Consignment means the exporter retains ownership of the rice until the importer sells it. Payment happens only after sale, which places nearly all financial risk on the supplier and is rarely used in bulk rice trade outside of trial shipments or promotional stock.
How a Letter of Credit Works for First-Time Suppliers
A letter of credit protects a Qatari importer working with a new rice supplier by making a bank, not the exporter’s word, responsible for verifying that shipment terms were met before money moves. This structure is why LCs remain the preferred instrument for larger rice orders between parties without a trading history, as outlined in this step-by-step guide to opening a letter of credit for rice import.
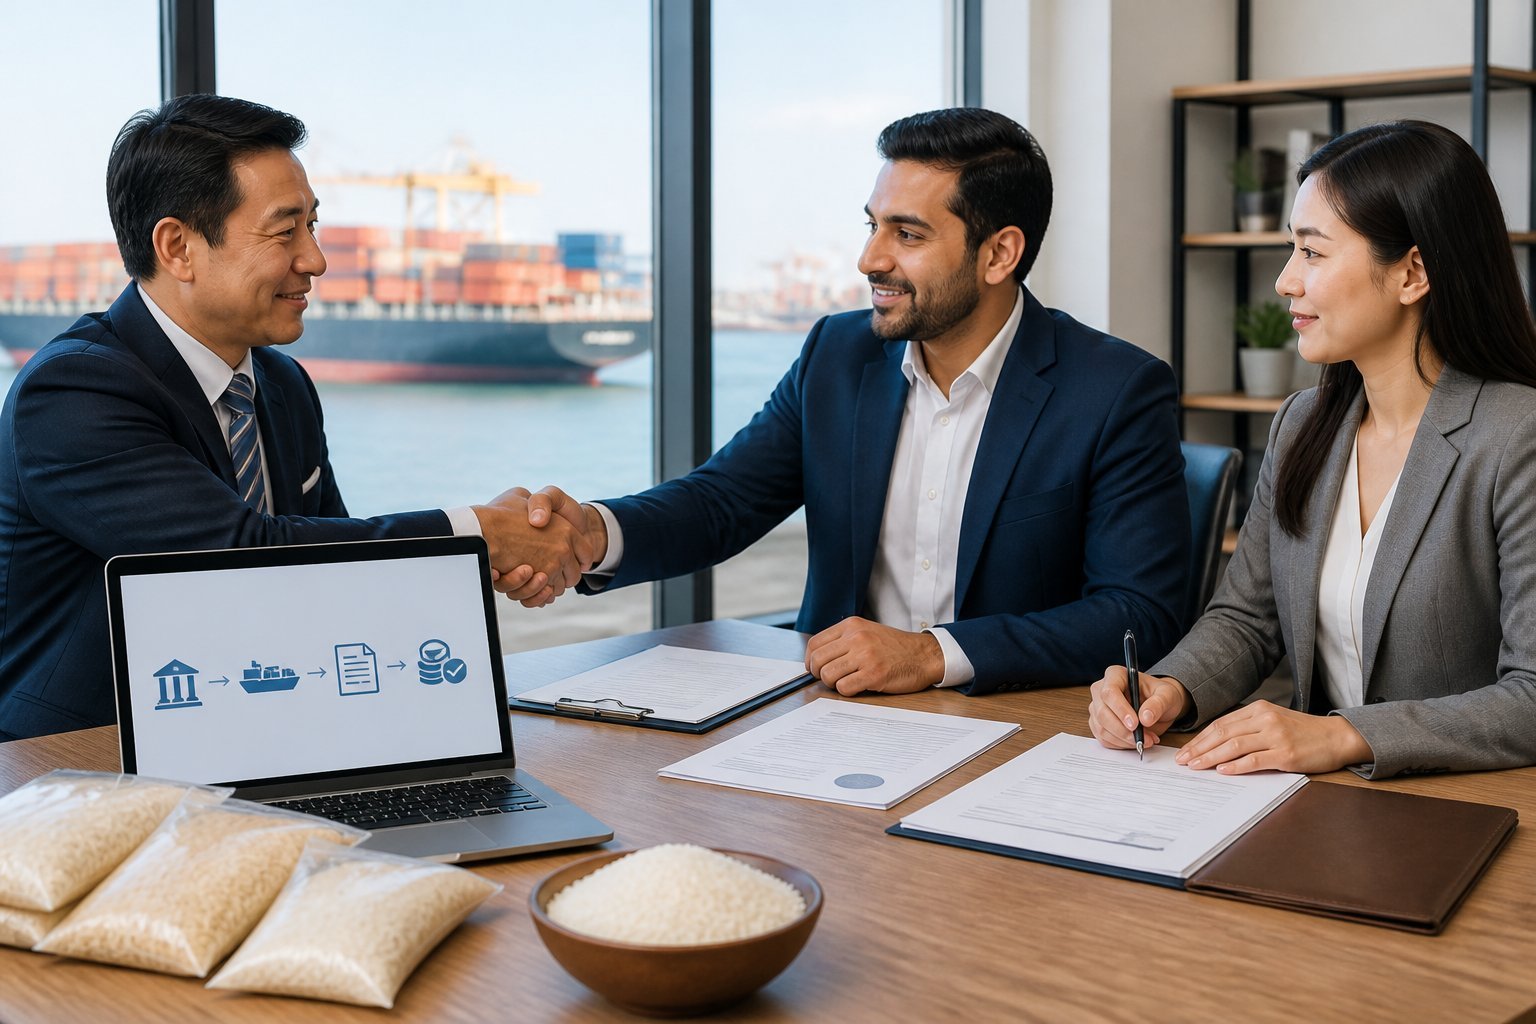
The LC process involves the importer’s bank, the exporter’s bank, SWIFT messaging to transmit terms, and a defined set of documents the exporter must present exactly as specified. Confirmation, discounting, and amendment fees are the main bank charges that add cost to this method, and they scale with the perceived risk of the issuing bank’s country, according to one exporter’s breakdown of LC costs in rice trade.
The Roles of the Issuing and Confirming Banks
The issuing bank, chosen by the Qatari importer, opens the LC and commits to paying once compliant documents arrive. A confirming bank, often located in the exporter’s country or a neutral trade hub, adds its own guarantee on top of the issuing bank’s promise. Confirmation matters most when the issuing bank sits in a country where the exporter’s bank will not accept payment risk without backup, a detail covered in this guide to letters of credit for rice trade.
Sight LC vs. Usance LC
A sight LC pays the exporter as soon as compliant documents are presented. A usance LC delays payment 30, 60, or 90 days after presentation, giving the Qatari importer extra time to sell or process the rice before funds leave the account. Usance terms suit importers managing tight working capital, but they cost the exporter financing time, which is usually reflected in the contract price.
How to Avoid Documentary Discrepancies
Discrepancies, even small ones like a misspelled name on a bill of lading, are the leading cause of delayed LC payments. Importers should specify document requirements clearly in the LC application and share a checklist with the supplier before shipment. Common issues include mismatched quantities, late presentation of documents, and certificates that do not match the LC’s exact wording, a pattern confirmed across multiple guides to LC discrepancies in trade finance.
Using TT Safely for Rice Purchases
Telegraphic transfer works safely for rice purchases when the payment is split into stages tied to verifiable shipping milestones, not paid in full upfront. TT is a straightforward SWIFT wire transfer, and its low bank charges make it attractive for repeat orders with a proven supplier, but a wire sent cannot be recalled if something goes wrong, as noted in this guide to safe TT structuring for produce imports.
Structuring an Advance and Balance Payment
A common structure has the Qatari importer send 30 percent as a TT advance against a proforma invoice, with the remaining 70 percent paid against a scanned bill of lading before the exporter releases original shipping documents. This keeps both sides exposed to only part of the contract value at any point.
When to Release Funds Against Shipping Evidence
Funds for the balance payment should move only after the buyer confirms shipment through a scanned or telexed bill of lading, matched against the commercial invoice and packing list. Releasing the balance before confirming the cargo actually loaded removes the protection TT structuring is meant to provide.
SWIFT Transfers, AML Checks, and Payment Delays
SWIFT wire transfers can face delays from anti-money laundering (AML) checks, especially when either bank flags the counterparty’s country for extra screening. Qatari importers should build a buffer of several business days into shipment schedules to account for compliance holds, since a wire flagged for review can sit for a week or more before clearing.
When CAD, D/P, and D/A Are Appropriate
Cash against documents and documents against payment fit rice orders where the buyer and seller trust each other enough to skip a bank guarantee but still want document control over cargo release. These middle-ground terms shift more risk toward the exporter than an LC does, since no bank promises payment if the buyer walks away.
Cash Against Documents and Documents Against Payment
CAD and D/P work the same way in practice: the exporter ships the rice and routes documents through banks, and the importer must pay in full before receiving the documents needed to clear cargo. If the Qatari buyer refuses to pay, the exporter’s rice sits at the destination port, a risk one exporter described after losing time and money on a stalled shipment, detailed in this account of a failed CAD transaction.
Why Documents Against Acceptance Carries More Seller Risk
Documents against acceptance (D/A) hands over shipping documents once the buyer simply signs a promise to pay later, rather than paying immediately. This gives the importer use of the cargo before payment is due, but leaves the exporter holding an unsecured IOU with no bank guarantee behind it, which is why many suppliers avoid offering D/A on first orders, according to this comparison of D/P and D/A terms in rice trade.
What Happens When a Buyer Does Not Take Up Documents
When a buyer refuses or delays taking up documents under CAD or D/P, the cargo accumulates demurrage charges at the destination port while the exporter searches for another buyer or arranges return shipment. This scenario is one of the strongest arguments for reserving CAD and D/A for buyers with a verified trading history, rather than first-time counterparties.
Documents That Control Cargo Release and Payment
The documents attached to a rice shipment determine both when payment is triggered and when cargo can legally clear customs in Qatar. Missing or mismatched paperwork is the most common reason payment gets delayed under any payment term, whether LC, CAD, or TT.
The Core Shipping Document Set
Every rice import relies on a core set of shipping documents: the bill of lading, commercial invoice, and packing list. These three establish what was shipped, its value, and how it was packed, and banks check them against the payment instrument’s exact wording before releasing funds or documents, a process detailed in this checklist for bulk rice import documentation.
Origin Inspection and Quality Certificates
A certificate of origin and phytosanitary certificate confirm where the rice came from and that it meets plant health standards for import into Qatar. An inspection certificate, often issued by an independent inspection company such as SGS, Cotecna, or Intertek, verifies quantity and quality before the cargo leaves the exporting country, giving Qatari buyers third-party confirmation that reduces reliance on the seller’s word alone. Buyers should also review how rice samples get approved before a bulk order to catch quality issues before payment terms are triggered.
Managing Partial Shipments and Transshipment
Partial shipments split one order across multiple vessels or dates, which requires payment terms and LC wording that explicitly allow it. Transshipment, where cargo moves through an intermediate port before reaching Qatar, needs similar advance approval in the contract and LC, since unauthorized transshipment can itself trigger a documentary discrepancy that delays payment.
How to Allocate Bank, Country, and Contract Risk
Risk in a rice import deal splits across three areas: the counterparty’s reliability, the strength of the banks involved, and the country conditions on both ends of the trade. Qatari importers who assess all three together, rather than relying on the payment term alone, avoid the most common causes of payment delays and disputes.
Checking Counterparty and Issuing-Bank Strength
A strong payment term backed by a weak bank offers less protection than it appears to on paper. Importers should confirm the exporter’s bank has a track record of processing LCs without excessive discrepancy claims, and exporters should do the same check on the importer’s issuing bank before accepting an unconfirmed LC.
Aligning Incoterms With the Payment Trigger
The Incoterm chosen for a rice shipment should match when payment is actually due. FOB, CFR, and CIF each shift cost and risk at different points in the shipping journey, and mismatching the Incoterm with the payment trigger can leave one party paying for insurance or freight they did not agree to, a point covered in this guide to Incoterms for rice buyers.
Putting Charges, Timelines, and Default Remedies in the Contract
Every rice import contract should state clearly who pays bank charges, what timeline applies to document presentation, and what remedy exists if either side defaults. Leaving these terms vague is one of the most common sources of dispute in rice trade contracts, and clear language protects both the importer’s cash flow and the exporter’s cargo.
Choosing Terms That Protect Supply and Working Capital
The right rice import payment term protects two things at once: a steady, reliable supply of rice and the working capital needed to keep the business running. Qatari importers who lean too heavily on open account terms risk supply disruption if a supplier’s own cash flow tightens, while those who over-rely on cash in advance tie up capital that could fund other orders.
Balancing the two means matching payment terms to the size and history of each supplier relationship rather than applying one standard term across the whole supply chain. A newer supplier might justify a confirmed LC or a TT split, while a long-term partner with a clean shipment record can move toward more flexible terms over time. For buyers managing multiple rice suppliers, reviewing how to choose a rice supplier alongside payment structure helps build a supply chain that holds up under both quality and financial pressure.
Frequently Asked Questions
Which payment term is safest for a first rice import order?
A confirmed letter of credit at sight is the safest option for a first rice import order, since a bank guarantees payment only after compliant documents are presented. For smaller first orders, a split TT with a partial advance and the balance against shipping documents offers a lower-cost middle ground.
Is TT safer than an LC for rice imports?
TT is not safer than an LC in terms of built-in protection, since a wire transfer carries no bank guarantee once sent. TT works well when the supplier relationship is already established and both parties agree on staged payments tied to shipping milestones.
What is the difference between CAD and D/P?
CAD and D/P describe the same basic mechanism: the buyer pays in full to receive shipping documents needed to clear cargo. Some traders use the terms interchangeably, though D/P is more common in formal documentary collection through banks.
What documents should an LC require for a rice shipment?
An LC for a rice shipment should require the bill of lading, commercial invoice, packing list, certificate of origin, phytosanitary certificate, and an inspection certificate from a recognized inspection company. Requiring exact document wording that matches the LC terms reduces the risk of discrepancies delaying payment.
Who pays bank charges under a rice import LC?
Bank charges under an LC are typically split by agreement in the contract, with the issuing bank’s charges falling on the importer and the advising or confirming bank’s charges falling on the exporter. This split should be stated clearly in the LC application to avoid disputes at settlement.
Can an importer use open account terms with a new rice supplier?
Open account terms are risky with a new rice supplier since the importer receives goods and documents before paying, leaving the exporter fully exposed. Most suppliers reserve open account terms for buyers with a proven history of on-time payment across several completed shipments.